Is Refinancing Worth It at 5.85%? How to Calculate Your Break-Even Point Within 18 Months
Advertisements
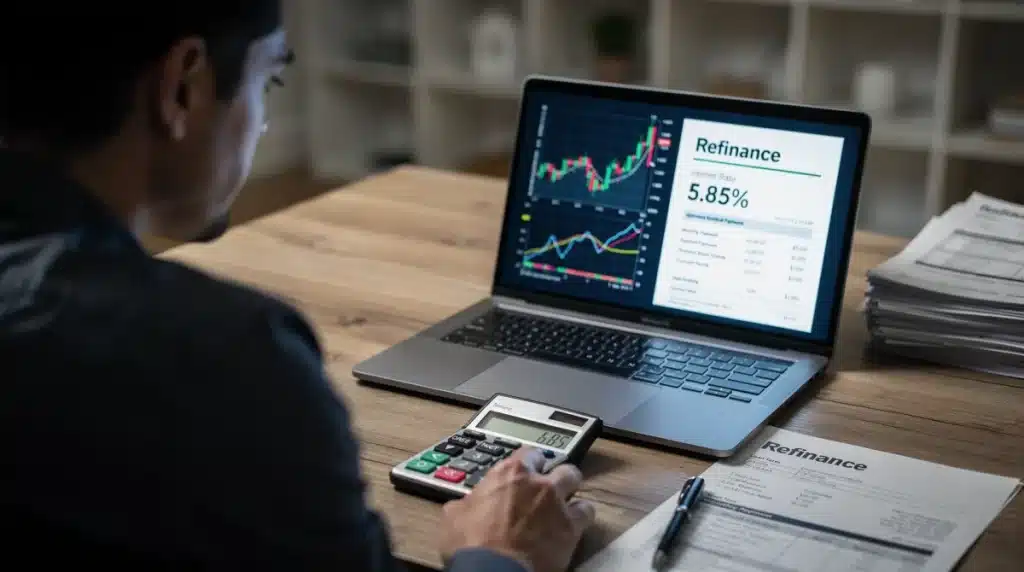
Thinking about swapping your current home loan for a lower monthly payment? With mortgage rates hovering around 5.85%, thousands of homeowners are asking if Refinancing Worth the upfront closing costs right now.
Finding the right answer comes down to a simple math formula: your break-even point. If monthly interest savings cover your lender fees within 18 months—and you plan to stay put—replacing your existing mortgage makes strong financial sense.
Discover how to run the exact numbers on your home equity, weigh hidden loan fees, and decide if locking in a 5.85% rate fits your long-term budget.
Advertisements
Understanding the 5.85% Rate in Today’s Market
The 5.85% interest rate, when considering a mortgage refinance, is a figure that warrants close inspection within the current economic climate. It represents a specific opportunity that may or may not align with individual financial objectives and market trends.
Current market conditions play a significant role in determining the attractiveness of this rate. Factors such as inflation, Federal Reserve policies, and broader economic stability all influence the overall interest rate environment.
For many homeowners, a 5.85% rate might be lower than their existing mortgage, signaling potential savings. However, it is essential to compare this rate not just against your current loan, but also against historical averages and future predictions.
Advertisements
The Current Interest Rate Landscape
Mortgage rates have seen considerable volatility over the past few years, influenced by global economic shifts and domestic policy decisions. A 5.85% rate could be seen as competitive, depending on when your original mortgage was secured.
Analysts suggest that while rates have stabilized somewhat, future movements remain uncertain. This makes the decision to refinance now at 5.85% a timely consideration for many.
Evaluating the rate against the backdrop of an evolving market helps homeowners understand the real value proposition. It’s about more than just the number; it’s about its position within the broader financial narrative.
Factors Influencing Refinance Rates
- Credit score and financial history heavily impact the specific rate offered.
- Loan-to-value (LTV) ratio, or the equity in your home, plays a critical role.
- Overall economic indicators, including inflation and employment data, influence lender offerings.
- The type of loan (fixed-rate vs. adjustable-rate) also affects the available rates.
Calculating Your Break-Even Point Within 18 Months
Determining if refinancing at 5.85% is worth it largely depends on calculating your break-even point. This metric reveals how long it will take for the savings from your lower interest rate to offset the costs associated with the refinancing process.
For many homeowners, aiming for a break-even point within 18 months is a strategic goal. This timeframe ensures that the financial benefits are realized relatively quickly, making the refinance a more attractive proposition.
The calculation involves a straightforward comparison of total closing costs against your monthly savings. A clear understanding of these figures is paramount to a sound financial decision.
To accurately assess if refinancing at 5.85% makes sense, you must gather all relevant financial information. This includes your current monthly mortgage payment, the new proposed monthly payment, and the total closing costs associated with the refinance.
The goal is to ensure that the cumulative monthly savings surpass the upfront costs within your desired 18-month window. This detailed calculation provides clarity and confidence in your decision-making process.
Many online calculators can assist with this, but understanding the underlying principles is key. It empowers you to verify the numbers and ensure they align with your specific financial situation and goals for refinancing at 5.85%.
Step-by-Step Break-Even Calculation
First, identify your total closing costs, which can include origination fees, appraisal fees, title insurance, and other administrative charges. These costs can vary significantly, so obtaining a detailed estimate from your lender is essential.
Next, calculate your monthly savings by subtracting your new proposed monthly payment from your current monthly payment. This difference represents the amount of money you will save each month by refinancing.
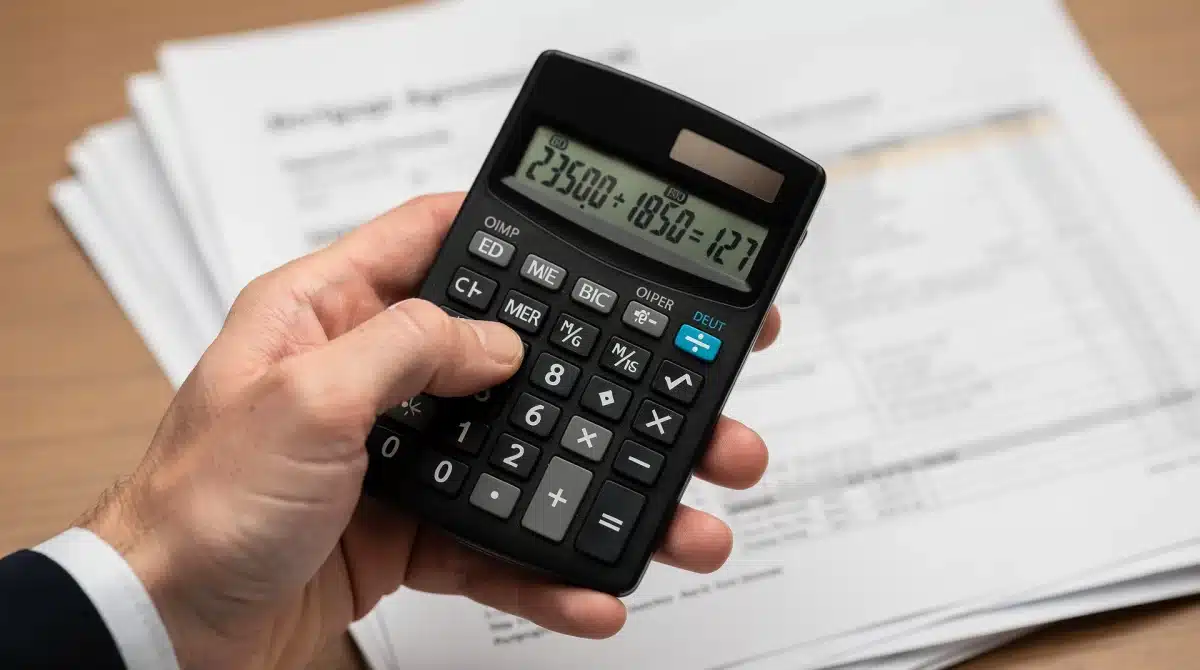
Finally, divide your total closing costs by your monthly savings. The result will be the number of months it takes to break even. If this number is 18 or less, then refinancing at 5.85% could be a favorable move.
What if the Break-Even Point Exceeds 18 Months?
- A longer break-even period might still be acceptable if you plan to stay in your home for many years.
- Consider if the lower monthly payment offers significant cash flow benefits despite a longer break-even.
- Evaluate if the refinance allows you to pay off your mortgage faster, even with higher upfront costs.
- A break-even point beyond 18 months requires a more thorough long-term financial projection.
Key Considerations Beyond the Numbers
While the break-even calculation is paramount, other factors significantly influence whether refinancing at 5.85% is truly worth it. These considerations extend beyond mere interest rates and delve into personal financial stability and future plans.
Understanding your long-term goals is critical. If you anticipate selling your home in the near future, a refinance might not provide sufficient time to recoup the costs, even with a favorable rate.
The overall impact on your financial health, including credit score implications and emergency fund status, should also be thoroughly evaluated. A holistic view ensures that refinancing at 5.85% aligns with your broader financial strategy.
Impact on Your Financial Goals
Refinancing at 5.85% can free up monthly cash flow, which can be redirected towards other financial objectives, such as paying down high-interest debt or boosting retirement savings. This strategic reallocation of funds can have a profound impact.
Conversely, if refinancing adds significant debt or extends your loan term without substantial benefit, it might hinder your progress towards financial independence. Always weigh the immediate gains against your long-term vision.
Careful planning ensures that the decision to refinance at 5.85% supports, rather than detracts from, your overall financial well-being. It’s about aligning your mortgage strategy with your life goals.
Market Volatility and Future Rates
The current financial environment is characterized by a degree of market volatility, which can influence future interest rates. While 5.85% might seem attractive now, it’s important to consider potential rate movements.
No one can predict the future with certainty, but staying informed about economic forecasts can provide valuable context. This helps in assessing the long-term viability of your refinancing decision.
A fixed rate of 5.85% offers stability against future rate hikes, which is a significant advantage for many homeowners. This certainty can be a powerful motivator, regardless of short-term market fluctuations.
The Refinancing Process: What to Expect
Embarking on a mortgage refinance journey at 5.85% involves several distinct steps, each requiring attention to detail. Understanding this process can help streamline your experience and minimize potential stress.
From application to closing, each stage has specific requirements and timelines. Being prepared with the necessary documentation and understanding the lender’s expectations will ensure a smoother transaction.
The process, while sometimes complex, is designed to protect both the borrower and the lender. Familiarity with these steps is crucial for anyone considering if refinancing at 5.85% is worth their effort.
Documentation and Application
The initial phase of refinancing at 5.85% involves gathering extensive financial documentation. Lenders require proof of income, asset statements, and detailed credit history to assess your eligibility and risk.
The application itself will ask for comprehensive personal and financial information. Transparency and accuracy during this stage are paramount to avoid delays and ensure a favorable outcome.
It’s advisable to have all your documents organized and readily available before you begin the application process. This proactive approach can significantly expedite the initial review.
Appraisal and Underwriting
- An appraisal determines the current market value of your home, impacting your loan-to-value ratio.
- Underwriting involves a thorough review of your financial profile and property details by the lender.
- Both steps are critical in determining final loan approval and the terms of your 5.85% refinance.
Potential Risks and How to Mitigate Them
While refinancing at 5.85% can offer significant benefits, it also comes with potential risks that homeowners must acknowledge. Being aware of these challenges allows for proactive mitigation strategies.
One primary risk involves the closing costs, which can be substantial and, if not properly managed, can erode the savings gained from a lower interest rate. Understanding these fees upfront is vital.
Another consideration is the potential for extending the loan term, which might increase the total interest paid over the life of the loan, even with a lower rate. Careful analysis of the new loan term is essential.
Managing Closing Costs
Closing costs are an unavoidable part of the refinancing process, but they can be managed. Shopping around for lenders can help you find more competitive fees and potentially negotiate certain charges.
Some lenders offer “no-closing-cost” refinances, where the fees are rolled into the loan amount or offset by a slightly higher interest rate. While this reduces upfront out-of-pocket expenses, it can increase the total amount repaid.
Always request a detailed breakdown of all closing costs to understand exactly what you are paying for. This transparency is key to determining if refinancing at 5.85% aligns with your financial goals.
Impact on Loan Term and Total Interest
Refinancing at 5.85% often involves taking out a new loan for a fresh term, typically 15 or 30 years. If you are already several years into your current mortgage, extending the term means you will be paying interest for a longer period.
Even with a lower interest rate, a longer loan term can result in paying more total interest over time. It’s crucial to compare the total interest paid on your current loan versus the proposed new loan.
Consider options like a shorter loan term to accelerate your debt repayment, even if it means a slightly higher monthly payment. This strategy can maximize the benefits of refinancing at 5.85%.
Alternatives to Refinancing at 5.85%
For some homeowners, refinancing at 5.85% might not be the most suitable option, or they may want to explore other financial strategies. Several alternatives exist that could address similar financial goals without the commitment of a full refinance.
These alternatives range from making extra payments on your current mortgage to exploring other forms of debt consolidation. Each option has its own set of advantages and disadvantages, tailored to different financial situations.
Understanding these alternatives provides a broader perspective, ensuring that you choose the most effective path for your unique circumstances. It’s about finding the best financial fit, not just following a trend.
Making Extra Mortgage Payments
One straightforward alternative is to simply make additional payments on your existing mortgage. Even small extra contributions can significantly reduce the principal balance and shorten the loan term.
This strategy avoids all closing costs associated with refinancing and directly reduces the total interest paid over the life of the loan. It offers flexibility and immediate financial benefit.
For those who find that refinancing at 5.85% doesn’t meet their break-even criteria, this can be a powerful tool. It allows you to accelerate debt repayment at your own pace.
Home Equity Loans or Lines of Credit (HELOCs)
- Home equity loans provide a lump sum, often with a fixed interest rate, for specific needs.
- HELOCs offer a revolving credit line, allowing flexible borrowing against your home equity.
- These options can be useful for debt consolidation or home improvements without changing your primary mortgage terms.
- They typically involve lower closing costs than a full mortgage refinance.
Expert Insights on Refinancing at 5.85%
Financial experts consistently emphasize the importance of personalized analysis when considering if refinancing at 5.85% is worth it. Their insights offer valuable perspectives beyond the raw numbers, focusing on strategic financial planning.
Many advisors suggest looking at your overall financial picture, not just the mortgage itself. This includes your emergency savings, retirement contributions, and other debt obligations.
The consensus among professionals is that a refinance should always serve a clear financial purpose, whether it’s reducing monthly payments, shortening the loan term, or consolidating debt.
When to Seek Professional Advice
If you are unsure about whether refinancing at 5.85% is the right move for you, seeking advice from a qualified financial advisor is highly recommended. They can provide tailored guidance based on your specific situation.
A professional can help you navigate complex calculations, understand the fine print of loan offers, and identify potential pitfalls. Their expertise can be invaluable in making a confident decision.
Don’t hesitate to consult with multiple lenders and advisors to get a comprehensive view of your options. This due diligence ensures you are making the best choice for your financial future.
Long-Term Financial Planning
Refinancing at 5.85% should always be viewed as part of a larger, long-term financial plan. It’s an opportunity to optimize your housing costs and free up resources for other investment or savings goals.
Consider how this decision impacts your retirement planning, college savings, or other significant life events. A well-executed refinance can provide a solid foundation for these future endeavors.
The goal is to leverage the current interest rate environment to your advantage, creating a more secure and prosperous financial future. It’s a strategic move with lasting implications.
| Key Point | Brief Description |
|---|---|
| Break-Even Calculation | Divide total closing costs by monthly savings to find months to recoup investment. |
| 18-Month Goal | Aim for break-even within 18 months for optimal short-to-medium term benefit. |
| Beyond Numbers | Consider long-term financial goals and market volatility alongside calculations. |
| Expert Consultation | Seek professional advice for personalized guidance and risk mitigation. |
Frequently Asked Questions About Refinancing at 5.85%
Refinancing at 5.85% can lower your monthly mortgage payments, reduce the total interest paid over the loan’s life if the term is shortened, or help you consolidate other debts. It can also convert an adjustable-rate mortgage to a stable fixed rate, providing financial predictability.
To calculate your break-even point, divide the total closing costs of the refinance by your monthly savings. For example, if costs are $3,000 and you save $150 per month, your break-even point is 20 months. Aim for this to be within 18 months for quick returns.
A less-than-perfect credit score might result in a higher interest rate than 5.85% or impact your eligibility. Focus on improving your credit score before applying by paying bills on time and reducing debt. Some lenders offer programs for those with fair credit, but rates may vary.
While lenders must disclose all fees, some costs might not be immediately obvious. These can include appraisal fees, title insurance, attorney fees, and loan origination fees. Always request a detailed Loan Estimate to understand all charges involved before committing to refinancing at 5.85%.
Refinancing at 5.85% may not be beneficial if you plan to sell your home soon, as you might not recoup closing costs. It’s also less ideal if the new rate isn’t significantly lower than your current one, or if extending your loan term substantially increases total interest paid over time.
What this means
The decision to evaluate if refinancing worth 5.85% demands a comprehensive understanding of both personal finances and market dynamics. Homeowners must go beyond merely comparing interest rates, delving into the intricacies of closing costs and their break-even point.
This strategic financial move, when executed thoughtfully, can unlock significant long-term savings and provide enhanced financial stability.
It is crucial to monitor economic indicators and consult with financial professionals to ensure the decision aligns with individual goals and current market realities, making it a proactive step towards optimizing one’s financial future.