Claiming Spousal Benefits at 67: Maximize Your Social Security
Advertisements
Latest developments on Social Security Spousal Benefits: How Claiming at Age 67 Secures 50% of Higher Earner Payouts, with key facts, verified sources and what readers need to monitor next in Estados Unidos, presented clearly in Inglês (Estados Unidos) (en-US).
Social Security Spousal Benefits: How Claiming at Age 67 Secures 50% of Higher Earner Payouts is shaping today’s agenda with new details released by officials and industry sources. This update prioritizes what changed, why it matters and what to watch next, in a straightforward news format.
Advertisements
Understanding Social Security Spousal Benefits at 67
For many married couples in the United States, navigating the complexities of Social Security benefits can significantly impact their retirement security. A key strategy often overlooked is the timing of claiming spousal benefits, particularly at age 67.
This specific age holds substantial importance as it represents the Full Retirement Age (FRA) for a large segment of the population, impacting how benefits are calculated and received. Understanding these nuances is vital for maximizing retirement income.
Claiming Social Security Spousal Benefits at age 67 can secure 50% of a higher-earning spouse’s primary insurance amount (PIA), a critical factor in long-term financial planning.
Advertisements
Eligibility Criteria for Spousal Benefits
To qualify for spousal benefits, several conditions must be met, ensuring that only eligible individuals receive these crucial payments. The primary earner must have already filed for their Social Security retirement benefits, or be deceased, for their spouse to claim.
Furthermore, the spouse claiming benefits must generally be at least 62 years old, though claiming before their own Full Retirement Age will result in a permanent reduction. For full spousal benefits, claiming at your own FRA is essential.
Marriage duration also plays a role; generally, you must have been married for at least one continuous year to be eligible for Social Security Spousal Benefits based on your spouse’s record.
Who Qualifies for Spousal Benefits?
- Married individuals whose spouse has filed for retirement benefits.
- Divorced individuals who were married for at least 10 years and are not currently remarried.
- Widows or widowers, who may claim benefits based on a deceased spouse’s record.
It is important to note that if you are eligible for benefits based on your own work record and on your spouse’s record, the Social Security Administration (SSA) will always pay your own benefit first. If your spousal benefit is higher, you will receive a combination that equals the higher spousal amount.
The Significance of Claiming at Age 67
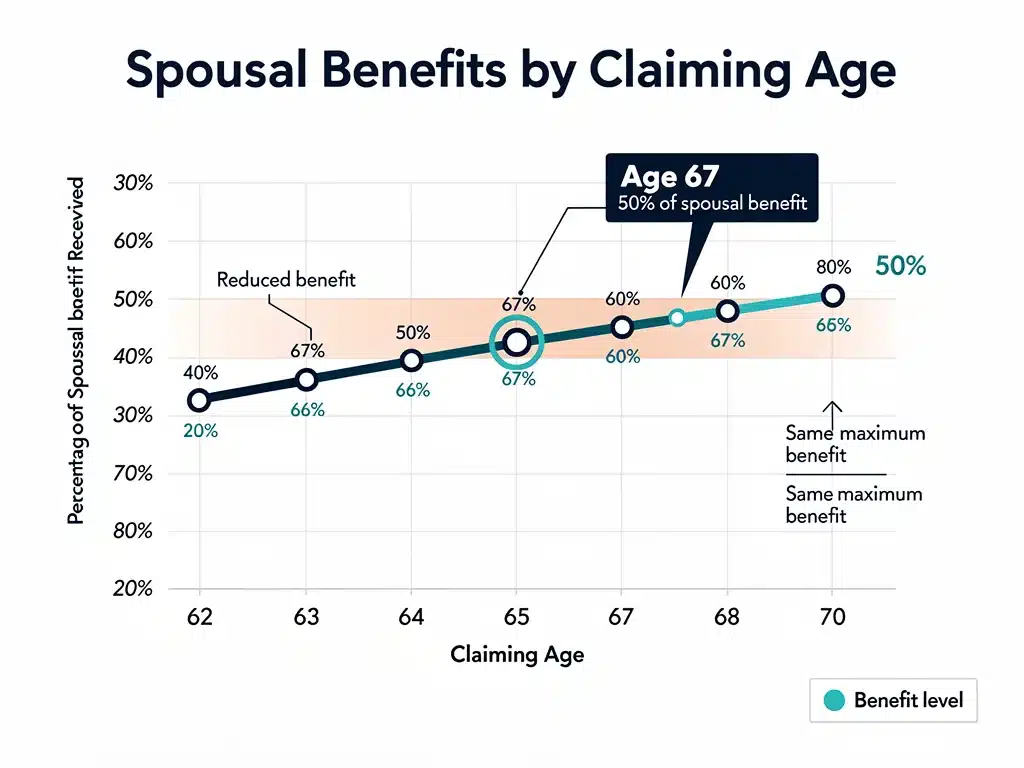
Age 67 stands out as the Full Retirement Age for those born in 1960 or later, making it a pivotal age for claiming full Social Security Spousal Benefits. Claiming at this age ensures you receive the maximum 50% of your spouse’s Primary Insurance Amount (PIA).
Claiming spousal benefits earlier than age 67, such as at age 62, will result in a reduced benefit amount, which is a permanent reduction. This reduction can significantly impact your total lifetime benefits.
Therefore, strategically waiting until age 67 can lead to a substantially higher monthly payment, providing greater financial stability throughout retirement and truly maximizing your Social Security Spousal Benefits.
Maximizing Your Payouts
The decision to claim spousal benefits should always be part of a broader retirement income strategy. Coordinating with your spouse on when each of you claims your respective benefits can yield optimal results for the household.
For example, if the higher earner delays claiming their own benefits past their FRA, their PIA continues to grow, which in turn can increase the potential spousal benefit for their partner. This interplay is crucial for maximizing total family benefits.
Understanding these interconnected claiming strategies is key to securing the highest possible Social Security Spousal Benefits and overall retirement income for both individuals in a couple.
Comparing Your Own Benefits vs. Spousal Benefits
Many individuals have their own work history and are eligible for Social Security benefits based on their earnings record. The Social Security Administration automatically pays the higher of the two benefit amounts: your own earned benefit or the spousal benefit.
It is crucial to compare your own Primary Insurance Amount (PIA) with 50% of your spouse’s PIA. If your own PIA is higher, you will claim based on your own record; otherwise, you will receive the spousal benefit, which supplements your own up to the higher amount.
This comparison requires careful calculation and understanding of your specific earnings history and your spouse’s, ensuring you make the most informed decision regarding your Social Security Spousal Benefits.
Impact of Dual Eligibility
- If your own benefit is greater than 50% of your spouse’s, you will receive your own benefit.
- If 50% of your spouse’s benefit is greater than your own, you will receive your own benefit plus an additional amount to reach the spousal benefit total.
- You cannot receive both your full earned benefit and your full spousal benefit simultaneously; it’s always the higher of the two, or a combination up to the spousal maximum.
The “file and suspend” strategy, which allowed an individual to file for their own benefits and then suspend them to earn delayed retirement credits while their spouse claimed spousal benefits, was largely eliminated for those born after January 1, 1954. This change highlights the importance of current rules when planning for Social Security Spousal Benefits.
The Role of Full Retirement Age (FRA)
Full Retirement Age (FRA) is a critical concept in Social Security, determining when you can receive 100% of your earned benefits or 50% of your spouse’s benefits without reduction. For those born in 1960 or later, FRA is age 67.
Claiming any Social Security benefit, including spousal benefits, before your FRA results in a permanent reduction in your monthly payment. This reduction is designed to offset the fact that you are receiving benefits for a longer period.
Therefore, understanding your specific FRA and aligning your claiming strategy with it is fundamental to maximizing your Social Security Spousal Benefits and avoiding unnecessary reductions.
Coordinating Spousal Benefit Strategies
Effective retirement planning often involves a coordinated approach to claiming Social Security benefits, especially for couples. The timing of each spouse’s claim can significantly impact the total benefits received over their lifetimes.
For example, if the higher-earning spouse delays claiming their own benefits until age 70, they accrue delayed retirement credits, increasing their own benefit and, consequently, the potential survivor benefit for their spouse. This strategy can be particularly powerful.
A lower-earning spouse might claim their own reduced benefits early, then switch to higher Social Security Spousal Benefits at their FRA once the higher-earning spouse files, if that proves to be the better option.
Strategic Claiming Scenarios
- Higher earner delays until 70, maximizing their own benefit and future survivor benefits.
- Lower earner claims their own benefit early, then switches to spousal benefits at FRA.
- Both spouses claim at their respective FRAs to receive their full earned or spousal benefits.
Consulting with a financial advisor specializing in Social Security can provide personalized guidance, helping couples navigate these complex decisions. Their expertise ensures that the chosen strategy aligns with individual financial goals and maximizes Social Security Spousal Benefits.
Impact of Divorce on Spousal Benefits
Divorce does not necessarily preclude an individual from claiming spousal benefits. If you were married for at least 10 years, are currently unmarried, and your ex-spouse is at least 62, you may be eligible.
Importantly, your ex-spouse’s decision to claim their own benefits does not affect your ability to claim divorced spousal benefits. You can claim based on their record even if they haven’t started receiving their own benefits, provided they are eligible.
This provision offers a crucial safety net for many divorced individuals, ensuring they can still access Social Security Spousal Benefits based on a former spouse’s work history, without requiring direct contact or permission from the ex-spouse.
Future Outlook and Policy Considerations
The landscape of Social Security benefits is subject to ongoing policy discussions and potential reforms. While the core structure of spousal benefits has remained relatively stable, future adjustments to eligibility or benefit calculations are always a possibility.
It is essential for current and future retirees to stay informed about any proposed legislative changes that could impact their Social Security Spousal Benefits. The Social Security Administration regularly updates its guidance and projections.
Staying abreast of these developments and planning accordingly can help individuals adapt their retirement strategies to ensure continued financial security.
| Key Point | Brief Description |
|---|---|
| Claiming Age 67 | Ensures 50% of higher earner’s PIA for Social Security Spousal Benefits. |
| Eligibility Rules | Spouse must be 62+, primary earner filed, marriage 1+ year. |
| Maximizing Payouts | Coordinate claiming ages with spouse for optimal household benefits. |
| Divorced Spousal Benefits | Available for ex-spouses married 10+ years, unmarried. |
Frequently Asked Questions About Spousal Benefits
Full Retirement Age (FRA) is the age at which you are entitled to 100% of your primary insurance amount or 50% of your spouse’s primary insurance amount without reduction. For those born in 1960 or later, FRA is 67, making it the optimal age to claim full Social Security Spousal Benefits.
Generally, your spouse must have filed for their own Social Security retirement benefits for you to claim spousal benefits on their record. There are specific exceptions, such as for divorced spouses, where you might be able to claim even if your ex-spouse has not yet filed, provided they are eligible.
The Social Security Administration will always pay you the higher of your own earned benefit or your spousal benefit. If your spousal benefit (50% of your spouse’s PIA) is higher than your own PIA, you will receive a combination that equals the higher spousal amount, ensuring you maximize your Social Security Spousal Benefits.
Yes, if you claim Social Security Spousal Benefits before your Full Retirement Age (FRA), your monthly benefit amount will be permanently reduced. The reduction percentage depends on how many months you are claiming before your FRA, making age 67 a key milestone.
If you were married for at least 10 years and are currently unmarried, you may be eligible for divorced spousal benefits. This does not affect your ex-spouse’s benefits, and you can often claim even if they have not yet filed, providing a critical financial option for many.
What this means
The intricate rules surrounding Social Security Spousal Benefits: How Claiming at Age 67 Secures 50% of Higher Earner Payouts underscore the importance of informed decision-making in retirement planning. As policy discussions continue, individuals must remain vigilant about potential changes and proactively seek guidance. Understanding these benefits is not just about maximizing income; it’s about securing a stable financial future.