Federal EV Tax Credit Rules Revised for 2026: Full $7,500 Incentive
Advertisements
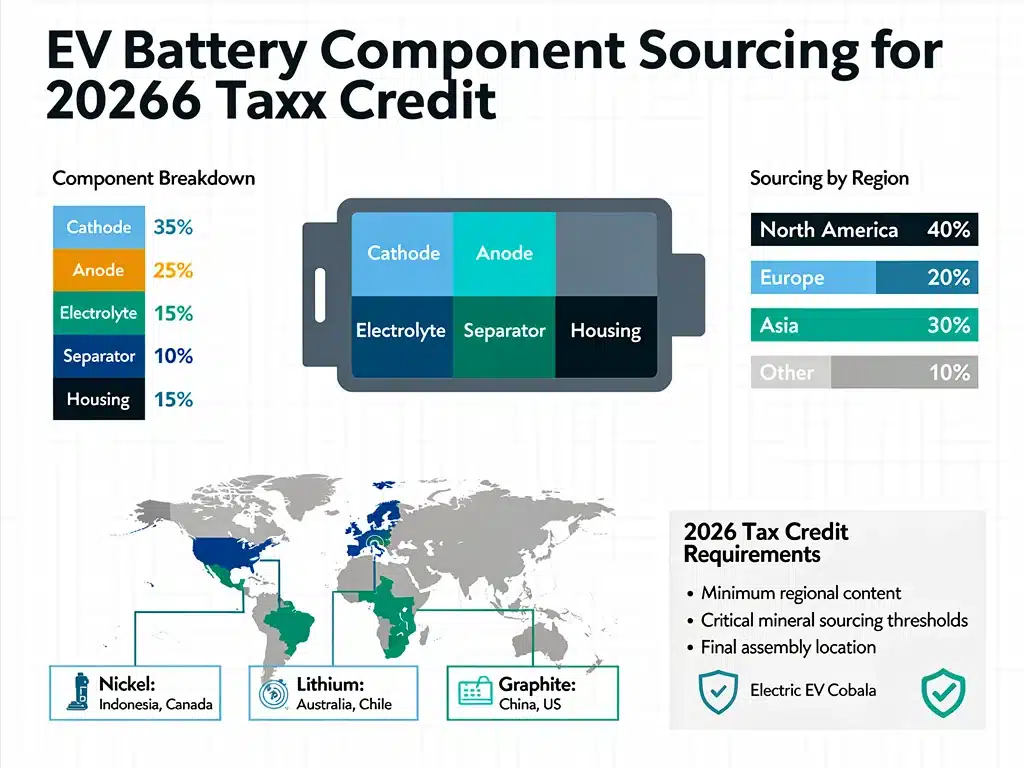
The 2026 Federal Clean Vehicle Tax Credit guidelines mandate strict sourcing thresholds under Internal Revenue Code Section 30D, requiring 70% of battery components to be manufactured or assembled in North America and 70% of critical minerals to be extracted or processed in the U.S. or free-trade partner nations to qualify for the full $7,500 incentive.
Additionally, vehicles must undergo final assembly in North America, adhere to MSRP caps of $80,000 for vans, SUVs, and pickups or $55,000 for sedans, and exclude battery inputs from designated Foreign Entities of Concern (FEOC).
Advertisements
Understanding the Revised Federal EV Tax Credit Rules for 2026
The landscape for electric vehicle (EV) incentives is set to undergo significant changes in 2026, with new criteria defining eligibility for the full $7,500 federal tax credit.
These revisions aim to bolster domestic manufacturing and reduce reliance on foreign supply chains, particularly concerning battery components.
Consumers and manufacturers alike must grasp these updated regulations to navigate the evolving market effectively.
Advertisements
The changes reflect a broader strategic shift towards a more resilient and localized EV ecosystem within the United States.
The Treasury Department and the IRS have provided initial guidance, outlining the critical stipulations that will determine which EVs qualify for the maximum incentive starting in 2026.
This move is poised to reshape consumer purchasing decisions and manufacturing strategies.
Key Changes to Battery Component Sourcing
A primary focus of the revised rules centers on the origin of EV battery components, a critical aspect for qualifying for the full tax credit.
The intent is to reduce dependency on certain foreign entities and strengthen domestic and allied supply chains.
Starting in 2026, a higher percentage of battery components must be manufactured or assembled in North America to unlock the full incentive.
This requirement directly impacts the cost structure for EV manufacturers and ultimately, the price point for consumers.
The specific thresholds for qualifying battery components will increase incrementally, demanding greater localization over time.
This phased approach allows the industry to adapt while steadily advancing the policy’s objectives.
Domestic Manufacturing Requirements Intensify
- A significant portion of the battery’s critical minerals must be extracted or processed in the U.S. or a free trade agreement country.
- Alternatively, these minerals can be recycled in North America to meet the stringent criteria.
- The value of battery components manufactured or assembled in North America must also meet rising percentages.
These stringent requirements are designed to incentivize substantial investment in North American manufacturing capabilities. The goal is to create a robust domestic supply chain for the burgeoning EV market, fostering job growth and economic stability.
Vehicle Assembly and Critical Mineral Mandates
Beyond battery components, the revised Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained also place emphasis on the final assembly location of the vehicle.
To qualify, the EV must undergo final assembly within North America.
Furthermore, critical minerals used in EV batteries face stricter sourcing rules, requiring a specific percentage to come from the U.S. or countries with which the U.S. has a free trade agreement.
This dual focus ensures that both the vehicle and its essential components align with the policy’s aims.
These mandates are not merely regulatory hurdles but strategic levers to decouple the U.S. EV industry from geopolitical vulnerabilities. They aim to secure a stable and ethically sourced supply of materials vital for future mobility.
Impact on EV Models and Consumer Choice
Consumers will find that not all EV models currently on the market will automatically qualify for the full $7,500 incentive under the 2026 rules.
The eligibility list is expected to narrow significantly as manufacturers adjust their supply chains.
This shift could influence purchasing decisions, pushing buyers towards models that meet the updated criteria. It also creates a competitive advantage for manufacturers already investing in North American production and sourcing.
The dynamic nature of these requirements means potential buyers should consistently check official resources for the most up-to-date list of qualifying vehicles.
Keeping informed will be crucial for maximizing the financial benefits of an EV purchase.
Navigating the Income and MSRP Limitations
The Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained also retain and, in some cases, refine income and Manufacturer’s Suggested Retail Price (MSRP) limitations.
These stipulations ensure that the tax credit benefits a broad range of consumers without subsidizing luxury vehicles excessively.
Individuals and joint filers must meet specific income thresholds to be eligible for the credit, preventing higher-income earners from claiming the incentive.
This aspect of the policy aims to promote equitable access to clean transportation options.
Additionally, vehicles exceeding certain MSRP caps will not qualify, regardless of their manufacturing or sourcing compliance.
This measure reinforces the goal of making EVs more accessible and affordable for mainstream consumers.
Income and Price Caps Defined
- For new clean vehicles, the MSRP cap is $80,000 for vans, SUVs, and pickup trucks, and $55,000 for other vehicles.
- The modified adjusted gross income (MAGI) limit is $300,000 for married couples filing jointly, $225,000 for heads of households, and $150,000 for all other filers.
- These caps apply to the year the vehicle is placed in service or the preceding tax year, whichever is less.
Understanding these financial limitations is as crucial as understanding the manufacturing requirements.
Prospective buyers should confirm both their income eligibility and the vehicle’s MSRP before making a purchase decision, ensuring they meet all criteria for the EV Tax Credit 2026.
The Role of the Inflation Reduction Act in 2026 Revisions
The 2026 revisions to the Federal EV Tax Credit Rules are largely a direct outcome of the Inflation Reduction Act (IRA) passed in 2022.
This landmark legislation introduced a comprehensive framework for clean energy incentives, with a strong emphasis on domestic production.
The IRA’s provisions are designed to accelerate the transition to electric vehicles by offering substantial financial incentives, but these incentives are strategically tied to strengthening the U.S. industrial base.
The phased implementation of these rules ensures a gradual but firm shift in manufacturing practices.
As 2026 approaches, the full impact of the IRA’s EV provisions will become more apparent, influencing everything from vehicle design to dealership inventories.
The legislation marks a pivotal moment for the American automotive industry and its supply chains.
Strategic Objectives of the IRA’s EV Provisions
The Inflation Reduction Act’s EV tax credit aims to achieve several strategic objectives.
Primarily, it seeks to reduce global emissions by encouraging EV adoption while simultaneously boosting American manufacturing capabilities and securing critical mineral supply chains.
This dual objective reflects a broader national interest in energy independence and economic resilience.
The incentives are not just about environmental benefits but also about creating high-paying jobs and fostering innovation within the U.S.
The long-term vision is to establish the United States as a global leader in EV production and technology, creating a sustainable and competitive domestic industry.
The 2026 rules are a critical step in realizing this ambitious goal for the EV Tax Credit 2026.
What the $7,500 Incentive Means for Consumers
For eligible consumers, the full $7,500 incentive can significantly reduce the effective cost of purchasing a new EV, making clean transportation more attainable.
This substantial saving can often bridge the price gap between electric and traditional gasoline-powered vehicles.
However, the complexity of the new rules means that not every EV purchase will automatically qualify for the full amount.
Consumers must perform due diligence, verifying both the vehicle’s compliance and their personal eligibility before committing to a purchase.
The incentive is applied as a non-refundable tax credit, meaning it can reduce a tax liability to zero, but any remaining credit is not returned as a refund.
This distinction is important for financial planning and understanding the true benefit of the EV Tax Credit 2026.
Planning for an EV Purchase in 2026
Prospective EV buyers planning for 2026 should start researching eligible models and understanding the evolving criteria now. Dealerships and manufacturers are also adapting, so staying in communication with them will be beneficial.
Consider models that are already known to have strong North American manufacturing ties or those whose manufacturers have explicitly committed to meeting the new sourcing requirements.
This proactive approach can save time and potential disappointment.
It is also wise to consult with a tax professional to understand how the credit will apply to your specific financial situation.
This personalized advice ensures that you maximize the benefits of the Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained.
Challenges and Opportunities for Manufacturers
The revised Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained present both significant challenges and substantial opportunities for automotive manufacturers.
Adapting supply chains to meet the strict domestic content requirements demands considerable investment and strategic restructuring.
Manufacturers must re-evaluate their entire production process, from mineral extraction to final assembly, to ensure compliance.
This often involves forging new partnerships, investing in North American facilities, and developing innovative recycling programs.
However, those who successfully navigate these changes stand to gain a competitive edge in the rapidly expanding EV market. Qualifying vehicles will be more attractive to consumers seeking to maximize their federal incentives.
Industry Adaptation and Investment
The industry is already responding with significant investments in U.S. and North American manufacturing facilities.
This includes battery plants, critical mineral processing facilities, and vehicle assembly lines, all aimed at securing eligibility for the EV Tax Credit 2026.
Collaboration between automakers and battery suppliers is becoming increasingly crucial to localize the entire supply chain.
This integrated approach is essential for meeting the complex requirements of the new rules and maintaining market share.
The long-term opportunity lies in establishing a resilient, self-sufficient North American EV ecosystem. This not only secures tax credit eligibility but also mitigates geopolitical risks and enhances the stability of production.
Anticipating the Market Impact of the 2026 Rules
The full implementation of the Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained is expected to have a profound impact on the U.S. automotive market.
Consumer purchasing patterns will likely shift towards compliant vehicles, influencing demand and production.
We may see a temporary reduction in the number of EV models eligible for the full credit as manufacturers adjust their operations. However, this is anticipated to be a short-term effect as the industry accelerates its localization efforts.
Ultimately, the revisions aim to foster a more robust and sustainable domestic EV market, aligning economic incentives with national strategic goals.
The changes will shape the availability, pricing, and overall competitiveness of electric vehicles in the coming years.
Monitoring the Evolving EV Landscape
Both consumers and industry stakeholders should closely monitor updates from the Treasury Department, the IRS, and automotive manufacturers as 2026 approaches.
The specifics of critical mineral sourcing and battery component percentages may still see further refinement.
Industry associations and consumer advocacy groups will also play a vital role in disseminating information and providing clarity on the evolving rules. Staying informed through official and reputable channels is paramount.
The transition to a fully localized EV supply chain is a complex undertaking, and the market will continue to evolve in response to these powerful incentives.
Understanding the Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained will be key to participating effectively in this transformation.
| Key Criterion | Description for 2026 |
|---|---|
| Battery Components | Increased percentage must be manufactured or assembled in North America. |
| Critical Minerals | Higher percentage sourced from U.S. or free trade agreement countries. |
| Vehicle Assembly | Final assembly must occur in North America. |
| Income/MSRP Limits | Continued income thresholds and vehicle price caps apply. |
Frequently Asked Questions About the 2026 EV Tax Credit
The rules primarily tighten eligibility for the $7,500 tax credit, focusing on where EV batteries and critical minerals are sourced, and where the vehicle’s final assembly occurs. These changes aim to boost North American manufacturing and reduce reliance on foreign supply chains, as mandated by the Inflation Reduction Act.
A significant percentage of battery components must be manufactured or assembled in North America. This requirement will increase incrementally through 2026, meaning fewer models may qualify initially, pushing manufacturers to localize their supply chains to meet the EV Tax Credit 2026 criteria.
Yes, the income and MSRP limitations remain in effect. These caps prevent higher-income earners and luxury vehicles from receiving the credit, ensuring the incentive primarily benefits a broader consumer base. Prospective buyers should verify both their income and the vehicle’s price against the current thresholds.
The official source for eligible vehicles will be the IRS website and the Department of Energy’s FuelEconomy.gov. These sites will provide the most current list of vehicles that meet the Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained, as manufacturers update their production and supply chains.
Start researching models now, paying close attention to their manufacturing origins and battery sourcing. Consult official government resources and a tax professional to understand your personal eligibility and how the Federal EV Tax Credit Rules Revised for 2026: Criteria for the Full $7,500 Incentive Explained will apply to your specific situation.
What This Means for the Future of EVs in the US
The revised Federal EV Tax Credit Rules represent a deliberate and strategic move to reshape the electric vehicle market in the United States.
These changes underscore a commitment to fostering domestic manufacturing, securing critical supply chains, and accelerating the transition to clean energy.
Consumers will need to be more informed than ever, carefully evaluating vehicles against the new criteria to ensure eligibility for the full $7,500 incentive.
The market will undoubtedly adapt, with manufacturers intensifying efforts to localize production and sourcing.
This evolving landscape signals a pivotal moment for the American automotive industry, driving innovation and investment within North America.
The long-term implications point towards a more resilient, self-sufficient, and competitive EV ecosystem, aligning economic growth with environmental goals.
To review official federal guidelines, vehicle eligibility criteria, and dealer transfer requirements, visit the IRS Clean Vehicle Tax Credits Information Portal.