Why Treasury Ladders Yielding 4.15% Beat Traditional Savings Accounts Under Current Federal Reserve Policy
Advertisements
Leaving your emergency cash in a traditional bank account often means settling for sluggish interest rates while inflation chips away at your balance. By building Treasury Ladders that yield 4.15%, savvy savers are locking in noticeably higher returns without sacrificing peace of mind.
This staggered government bond strategy spreads your money across multiple maturity dates, giving you regular liquidity alongside predictable fixed-income payouts. Under current Federal Reserve policy, short-term T-bills consistently outpace standard retail deposit rates.
Even better, interest earned on U.S. government securities is exempt from state and local taxes, stretching your real yield further. Here is how this low-risk approach beats conventional banking and how you can set one up.
Advertisements
Understanding the Current Federal Reserve Policy Landscape
The Federal Reserve’s monetary policy plays a pivotal role in shaping interest rates across the financial spectrum. Recent tightening cycles have pushed short-term rates higher, creating a more attractive environment for certain fixed-income investments.
These policy adjustments directly influence the yields offered by Treasury bills, notes, and bonds, making them increasingly competitive. Traditional savings accounts, however, often lag in adjusting their rates, presenting a clear disadvantage for savers.
The sustained efforts by the Federal Reserve to manage inflation and stabilize the economy have inadvertently created opportunities for investors willing to look beyond conventional banking products.
Advertisements
This policy backdrop forms the fundamental reason why Treasury Ladders yielding 4.15% are gaining prominence.
The Mechanics of Treasury Ladders Explained
A Treasury ladder involves investing in a series of Treasury securities with staggered maturity dates. For example, an investor might purchase Treasury bills maturing in 3 months, 6 months, 9 months, and 12 months, or longer-term notes.
As each security matures, the principal is reinvested into a new security at the longest rung of the ladder, maintaining a continuous stream of maturing investments.
This strategy offers a balance of liquidity and higher yields, especially in an environment where interest rates are elevated or expected to remain so.
The primary advantage lies in mitigating interest rate risk while capitalizing on current market rates.
Unlike a single long-term bond, a ladder ensures that a portion of the investment is regularly available for reinvestment at prevailing rates, which can be particularly beneficial when rates are rising or high.
How Staggered Maturities Enhance Returns
By staggering maturities, investors avoid locking all their funds into a single interest rate for an extended period. This allows them to capture potentially higher rates as shorter-term securities mature and are reinvested.
This method ensures a consistent cash flow from maturing investments, which can be reallocated based on market conditions. It provides flexibility that a single bond or a traditional savings account simply cannot match, especially when considering the current Federal Reserve policy impact.
- Diversification of maturity dates reduces overall interest rate risk.
- Regular reinvestment opportunities allow for capturing higher prevailing yields.
- Provides predictable income streams from maturing securities.
- Offers greater control over liquidity compared to long-term, illiquid investments.
Why Treasury Ladders Offer Superior Yields
The 4.15% yield observed in well-constructed Treasury ladders significantly surpasses the average interest rates offered by traditional savings accounts. This differential is a direct consequence of the Federal Reserve’s hawkish stance on interest rates, which has driven up Treasury yields.
Banks, while also affected by Fed policy, are often slower to pass on higher rates to their savings account holders. Their business models rely on a spread between lending and deposit rates, which means they prefer to keep deposit rates lower to maintain profitability.
Consequently, money held in savings accounts often loses purchasing power to inflation, even with nominal interest gains. Treasury Ladders yielding 4.15% provide a more robust defense against inflation while offering a tangible return on investment.
Comparing Treasury Yields to Savings Account Rates
As of recent data, the national average for savings account interest rates hovers significantly below 1%, with many large banks offering even less. In stark contrast, short-term Treasury bills have consistently offered yields above 4% for several months.
This discrepancy highlights a clear opportunity for investors to optimize their returns without taking on excessive risk. Treasury securities are backed by the full faith and credit of the U.S. government, making them one of the safest investments available.
- Treasury yields directly reflect Federal Reserve policy adjustments more quickly.
- Savings account rates are often sticky and slow to respond to market changes.
- The safety of U.S. government backing provides peace of mind for investors.
- Higher yields help preserve purchasing power against inflationary pressures.
This makes the argument for Why Treasury Ladders Yielding 4.15% Beat Traditional Savings Accounts even stronger, as the risk-adjusted returns are undeniably superior.
Liquidity and Flexibility: A Key Advantage
One common misconception about fixed-income investments is a lack of liquidity. However, a properly structured Treasury ladder provides substantial liquidity. As each rung of the ladder matures, funds become available, which can then be reinvested or used for other purposes.
This contrasts with a single Certificate of Deposit (CD) or a long-term bond, where funds are typically locked in until maturity, often with penalties for early withdrawal. Savings accounts offer immediate liquidity, but at the cost of significantly lower returns.
The flexibility of a Treasury ladder allows investors to adapt to changing financial needs or market conditions. Should interest rates rise further, maturing funds can be reinvested at even higher yields, enhancing overall portfolio performance.
Adapting to Economic Shifts with a Ladder Strategy
In an environment where economic forecasts can shift rapidly, the adaptive nature of a Treasury ladder is invaluable. It allows investors to dynamically adjust their investment strategy without incurring significant penalties or losing out on potential gains.
This is particularly relevant under the current Federal Reserve policy, which has demonstrated a willingness to adjust rates based on incoming economic data. The ability to roll over funds at new rates as they become available is a powerful tool for financial optimization.
The continuous cycle of maturities and reinvestments ensures that an investor’s capital is always working efficiently, capturing the best available rates without sacrificing access to funds. This strategic advantage solidifies the case for Treasury Ladders.
Tax Implications and Efficiency
Another compelling reason Why Treasury Ladders Yielding 4.15% Beat Traditional Savings Accounts involves their favorable tax treatment. Interest earned on Treasury securities is exempt from state and local income taxes, though it is subject to federal income tax.
This tax advantage can significantly boost the after-tax returns, especially for residents in high-tax states. In contrast, interest earned on traditional savings accounts is typically subject to federal, state, and local income taxes, reducing the net gain for investors.
When comparing the effective yield, factoring in tax benefits, the advantage of Treasury ladders becomes even more pronounced. This makes them a more tax-efficient investment vehicle for many U.S. investors.
Maximizing After-Tax Returns with Treasuries
For investors seeking to maximize their overall return, understanding the tax implications of different investment vehicles is crucial.
The state and local tax exemption for Treasuries can translate into hundreds or even thousands of dollars in savings annually, depending on the investment amount and individual tax bracket.
This aspect often goes overlooked when individuals simply compare nominal interest rates. A comprehensive financial analysis reveals that the tax efficiency of Treasury ladders contributes significantly to their superior performance against traditional savings accounts.
- State and local tax exemption enhances net returns.
- Traditional savings account interest is fully taxable.
- Tax benefits become more significant in high-tax states.
- Understanding tax implications is key to optimizing investment strategies.
Therefore, when evaluating the total value proposition, Treasury Ladders yielding 4.15% offer a clear edge in terms of both yield and tax efficiency.
Considerations for Implementing a Treasury Ladder
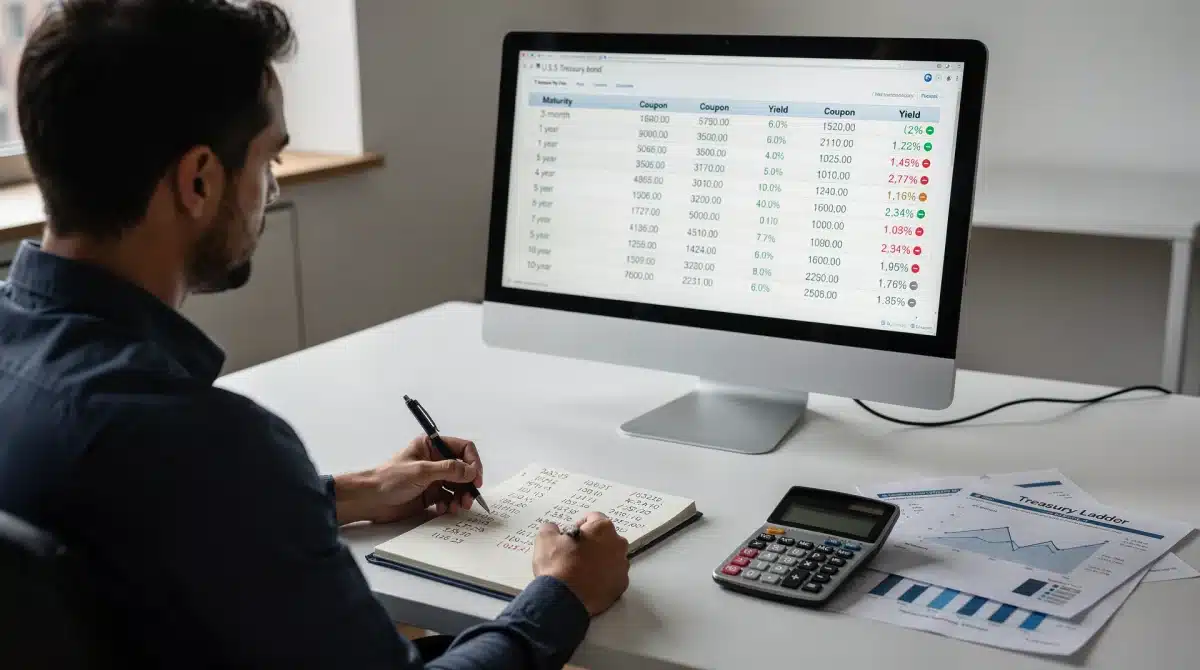
While the benefits are clear, implementing a Treasury ladder requires some planning. Investors need to determine their desired cash flow, the length of their ladder, and the specific Treasury securities they wish to include.
Online brokerage platforms and TreasuryDirect.gov make it relatively easy for individual investors to purchase Treasury securities directly.
It’s important to monitor Federal Reserve announcements and economic data, as these factors can influence future interest rate movements. While a ladder strategy is designed to be resilient to rate changes, staying informed allows for optimal reinvestment decisions.
For those new to fixed-income investing, starting with a shorter ladder and gradually extending maturities as comfort and understanding grow can be a prudent approach. This allows investors to gain experience while benefiting from higher yields.
Getting Started with Your Own Treasury Ladder
The first step involves assessing your current financial situation and liquidity needs. Decide how much capital you want to allocate to the ladder and over what time horizon you need access to portions of that capital.
Next, research current Treasury yields for various maturities to identify the most attractive options. Many financial news outlets and government websites provide up-to-date yield information.
Setting up an account with TreasuryDirect or a reputable brokerage is the final step to begin purchasing securities.
Remember, the goal is to create a diversified maturity schedule that aligns with your financial objectives, ensuring that Treasury Ladders becomes a tangible benefit for your portfolio.
The Long-Term Outlook for Treasury Ladders
Looking ahead, the long-term outlook for Treasury ladders remains positive, especially as the Federal Reserve continues to navigate economic conditions. While interest rates may fluctuate, the fundamental advantages of liquidity, safety, and competitive yields will persist.
Treasury ladders offer a resilient strategy against market volatility and inflation, providing a stable component within a diversified investment portfolio. Their ability to adapt to changing rate environments ensures that investors can consistently seek optimal returns.
For investors prioritizing capital preservation and consistent income, a Treasury ladder is likely to remain a cornerstone strategy. It stands as a testament to prudent financial planning in an ever-evolving economic landscape.
Sustained Relevance in Future Financial Planning
As financial markets mature and become more complex, the simplicity and effectiveness of a Treasury ladder continue to underscore its value. It provides a clear, understandable path to enhanced returns compared to traditional savings vehicles.
The ongoing dialogue around Federal Reserve policy and inflation control only reinforces the relevance of strategies that offer both security and yield. The sustained interest in Treasury ladders yielding 4.15% is a clear indicator of their perceived value by informed investors.
This strategy is not merely a short-term reaction to current rates but a foundational approach to managing wealth efficiently over the long haul. It is a strategic move that aligns with the objectives of many seeking stability and growth.
| Key Point | Brief Description |
|---|---|
| Higher Yields | Treasury ladders offer 4.15% vs. sub-1% for savings accounts. |
| Enhanced Liquidity | Staggered maturities provide regular access to funds. |
| Tax Advantages | Interest is exempt from state and local income taxes. |
| Federal Reserve Impact | Current policy drives up Treasury yields, widening the gap. |
Frequently Asked Questions About Treasury Ladders
A Treasury ladder is an investment strategy where you purchase multiple Treasury securities with different maturity dates. As each security matures, the principal is reinvested into a new security at the longest end of the ladder, creating a continuous cycle of maturing investments.
Current Federal Reserve policy has led to higher interest rates, which directly benefits Treasury yields. This makes the 4.15% yield on Treasury ladders significantly more competitive than the much lower rates offered by traditional savings accounts, optimizing returns for investors.
Yes, Treasury ladders offer good liquidity. As each rung of the ladder matures, a portion of your investment becomes available. This flexibility allows you to access funds or reinvest them at prevailing rates, providing more control than single long-term bonds or CDs.
Interest earned on Treasury securities is exempt from state and local income taxes, though it is subject to federal income tax. This tax advantage can lead to higher after-tax returns compared to traditional savings accounts, which are typically subject to all levels of income tax.
You can start by assessing your financial goals and liquidity needs. Then, you can purchase Treasury bills, notes, or bonds directly through TreasuryDirect.gov or via a brokerage account, selecting various maturity dates to build your staggered investment portfolio effectively.
What this means
The current financial landscape underscores a significant shift, highlighting why Treasury Ladders yielding 4.15% beat traditional savings accounts under current Federal Reserve policy.
This means investors have a clear opportunity to optimize their returns while maintaining safety and liquidity.
It is crucial to monitor ongoing Federal Reserve announcements and economic indicators, as these will continue to shape the yield environment.
Adapting investment strategies to leverage these higher Treasury yields can lead to substantial financial benefits, reinforcing the importance of informed decision-making in personal finance.