New Homebuyer Benefits 2026: 3 Federal Programs Offering Significant Aid (RECENT UPDATES)
Advertisements
To tackle ongoing housing affordability challenges, federal agencies have updated key assistance initiatives for aspiring homeowners.
New Homebuyer Benefits details updated eligibility criteria, down payment grants, and reduced interest rate options available through primary federal loan programs.
Understanding the Landscape of Federal Homebuyer Aid
The federal government has consistently played a pivotal role in shaping the housing market through various initiatives designed to support aspiring homeowners.
Advertisements
These programs aim to alleviate financial burdens, making the dream of owning a home a tangible reality for millions. The focus remains on sustainable homeownership and economic stability.
As 2026 approaches, several key federal programs are undergoing significant updates, reflecting evolving economic conditions and housing demands.
These adjustments are critical for potential buyers to comprehend, as they directly impact eligibility, available aid, and the application process. Staying informed is the first step toward leveraging these opportunities effectively.
Advertisements
The recent changes underscore a broader strategy to enhance housing affordability and equity, particularly for demographics historically facing barriers to homeownership.
These reforms are not merely bureaucratic tweaks but substantive improvements designed to broaden access and provide more robust support. The New Homebuyer Benefits are at the forefront of this effort.
Program 1: Federal Housing Administration (FHA) Loans – Enhanced Accessibility
The Federal Housing Administration (FHA) loan program remains a cornerstone of federal support for homebuyers, particularly those with lower credit scores or limited down payments.
Recent updates for 2026 aim to further enhance the program’s accessibility and flexibility, responding to contemporary market challenges. These changes are designed to open doors for a wider demographic.
Key modifications include adjustments to mortgage insurance premiums and revised guidelines for debt-to-income ratios, potentially allowing more applicants to qualify.
The objective is to balance risk mitigation with expanded opportunity, ensuring the program serves its intended purpose effectively. These enhancements reflect a proactive approach to supporting the housing market.
Furthermore, there’s a renewed emphasis on simplifying the application process and providing clearer guidance to lenders, which should translate into a smoother experience for borrowers.
The FHA’s commitment to facilitating homeownership is evident in these targeted improvements. The New Homebuyer Benefits prominently feature these FHA adjustments.
Key FHA Loan Updates for 2026
Mortgage insurance premium structures are being re-evaluated to reduce the overall cost of homeownership for eligible borrowers. This could translate into significant long-term savings, making monthly payments more manageable.
The goal is to make FHA loans an even more attractive option.
New guidelines on credit score requirements are being introduced, aiming to provide a more holistic assessment of an applicant’s financial readiness.
This moves beyond a singular reliance on credit scores, considering other financial indicators. It’s about a more inclusive evaluation for aspiring homeowners.
- Lowered annual mortgage insurance premiums for most borrowers.
- Flexible credit score considerations for a broader range of applicants.
- Streamlined documentation requirements to expedite the loan approval process.
- Increased loan limits in high-cost areas to reflect current market values.
These updates are expected to make FHA loans even more competitive and appealing to a diverse pool of first-time homebuyers.
The program’s evolution ensures it remains relevant and impactful in today’s dynamic housing environment. The New Homebuyer Benefits highlight these crucial changes.
Program 2: USDA Rural Development Loans – Expanding Opportunities
The United States Department of Agriculture (USDA) Rural Development loan program is vital for promoting homeownership in rural and suburban areas, offering zero-down-payment options to eligible borrowers.
For 2026, the program is set to expand its reach and refine its eligibility criteria, reflecting population shifts and economic growth in these regions. This expansion is crucial for rural communities.
Updates include a re-evaluation of eligible rural areas, potentially encompassing more communities that have experienced growth but still qualify under the program’s mandate.
This strategic adjustment aims to ensure that the benefits reach areas where they are most needed and can foster sustainable development. The USDA’s role in rural revitalization remains central.
Furthermore, there are efforts to streamline the application process for USDA loans, reducing bureaucratic hurdles and making it easier for qualified individuals to access financing.
These improvements are designed to increase the program’s efficiency and impact. The New Homebuyer Benefits include these important USDA modifications.
Geographic and Income Eligibility Adjustments
The definition of ‘rural’ is being updated to reflect current demographic and economic realities, potentially broadening the scope of eligible properties.
This ensures the program remains relevant as communities evolve and urban boundaries expand. More areas will likely benefit from these changes.
Income limits are also being revised to account for regional variations in cost of living and median incomes, ensuring that the program serves those genuinely in need of assistance.
This personalized approach acknowledges the diverse economic landscapes across the country. It’s a more equitable system for applicants.
- Expanded geographic eligibility to include more developing rural and suburban areas.
- Adjusted income limits to better reflect local economic conditions and cost of living.
- Enhanced educational resources for borrowers on rural homeownership and property maintenance.
- Quicker processing times for applications through digital platform improvements.
These changes are expected to significantly boost homeownership rates in designated rural areas, contributing to economic stability and community development.
The USDA remains a powerful tool for supporting growth outside major metropolitan centers. The New Homebuyer Benefits highlight these key developments.
Program 3: VA Home Loans – Continued Support for Veterans
The Department of Veterans Affairs (VA) home loan program continues to be an invaluable benefit for eligible service members, veterans, and surviving spouses, offering no-down-payment loans with competitive interest rates.
While largely stable, the 2026 outlook includes refinements aimed at enhancing the user experience and expanding access to specialized housing solutions. This unwavering support for veterans is paramount.
Recent discussions focus on improving the efficiency of the VA appraisal process and providing clearer guidance on property requirements, especially for energy-efficient homes or those requiring minor repairs.
The goal is to ensure veterans can access suitable housing without unnecessary delays. The VA’s commitment to its beneficiaries is unwavering.
Additionally, there’s an ongoing effort to better integrate VA home loan benefits with other federal and state programs, creating a more comprehensive support system for veterans transitioning into homeownership.
These synergistic approaches maximize the impact of available aid. The New Homebuyer Benefits will further solidify the VA’s role.
Streamlining Processes and Expanding Options
Efforts are underway to digitize more aspects of the VA loan application and approval process, reducing paperwork and accelerating closing times.
This modernization aims to provide a more seamless experience for service members and veterans. Efficiency is a key focus for these updates.
The VA is also exploring partnerships with housing counseling agencies to offer more tailored pre-purchase education and post-purchase support, helping veterans navigate the complexities of homeownership.
This holistic approach ensures long-term success for veterans. It’s about more than just securing a loan.
- Improved appraisal guidelines to reflect modern housing standards and features.
- Enhanced integration with state-level veteran housing assistance programs.
- Expanded access to adaptive housing grants for veterans with disabilities.
- Digital platform upgrades for faster loan processing and document submission.
These refinements underscore the VA’s continuous commitment to providing robust and accessible homeownership benefits to those who have served the nation.
The program remains a gold standard for veteran support. The New Homebuyer Benefits ensure veterans continue to receive top-tier assistance.
Navigating Eligibility and Application Processes
Understanding the specific eligibility requirements for each federal program is paramount for any aspiring homebuyer.
While all programs aim to facilitate homeownership, their criteria can vary significantly based on income, location, credit history, and military service. Thorough review of these guidelines is essential before initiating any application.
The application process itself often involves multiple steps, from pre-qualification to loan closing, and requires diligent documentation.
Familiarizing oneself with the necessary paperwork and timelines can significantly streamline the journey. Seeking guidance from approved lenders or housing counselors is highly recommended to avoid common pitfalls.
Prospective homebuyers should also be aware that program requirements can evolve, especially with the New Homebuyer Benefits.
Regularly checking official government websites and consulting with knowledgeable professionals ensures access to the most current and accurate information. Proactive engagement is key to success.
The Impact on First-Time Homebuyers
First-time homebuyers stand to benefit substantially from the recent and upcoming changes to federal programs.
These initiatives are often specifically tailored to address the unique challenges faced by individuals entering the housing market for the first time, such as limited savings for a down payment or less-than-perfect credit.
The focus on this demographic is clear.
The enhanced accessibility and flexibility of programs like FHA and USDA loans mean that a broader segment of the population can now realistically consider homeownership.
These programs provide crucial pathways that might otherwise be inaccessible. It’s a game-changer for many aspiring homeowners.
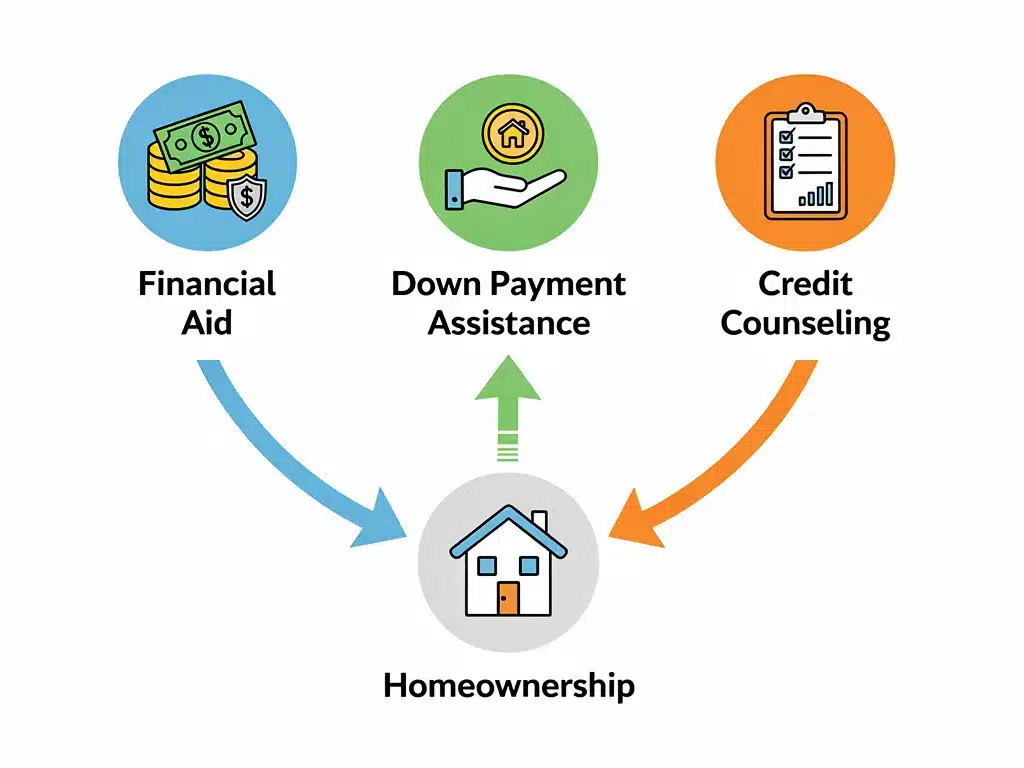
Moreover, the emphasis on educational resources and counseling services within these programs empowers first-time buyers with the knowledge and tools needed for successful and sustainable homeownership.
This holistic support extends beyond just financial aid. The New Homebuyer Benefits are truly transformative for this group.
Future Outlook and Economic Implications
The continued evolution of federal homebuyer programs, particularly the New Homebuyer Benefits, carries significant economic implications.
By expanding access to homeownership, these initiatives can stimulate local economies through increased construction, job creation, and consumer spending. A robust housing market benefits everyone.
A more inclusive housing market also contributes to greater wealth creation and financial stability for families, which can have ripple effects across communities.
Homeownership often represents the largest asset for many households, providing a foundation for long-term economic security. These programs foster upward mobility.
However, careful monitoring of market conditions and program effectiveness will be crucial to ensure these benefits are sustainable and do not inadvertently contribute to housing bubbles or other market imbalances.
The federal government aims for responsible growth and stability. The New Homebuyer Benefits are designed with these considerations in mind.
| Key Program | Recent Updates/Focus |
|---|---|
| FHA Loans | Enhanced accessibility, lower premiums, flexible credit. |
| USDA Rural Development | Expanded geographic and income eligibility for rural areas. |
| VA Home Loans | Streamlined processes, improved appraisals, expanded options. |
| Overall Impact | Increased homeownership access, economic stimulation, wealth creation. |
Frequently Asked Questions About New Homebuyer Benefits 2026
The primary goals are to enhance homeownership accessibility for first-time buyers and underserved communities, stimulate the housing market, and foster long-term economic stability. These benefits aim to address current affordability challenges and broaden the path to sustainable homeownership for a wider range of Americans.
Eligibility varies by program. FHA loans generally target buyers with lower credit scores or limited down payments. USDA loans are for rural and eligible suburban areas based on income and location. VA loans are exclusively for eligible service members, veterans, and their surviving spouses. Specific criteria are subject to recent updates.
The updates aim to make down payments more manageable. FHA loans continue to offer low down payment options, while USDA and VA loans often feature zero-down payment requirements for qualified borrowers. The recent changes seek to maintain or further reduce these barriers, enhancing financial flexibility for new homeowners.
For the most current and accurate information, it is highly recommended to consult the official websites of the Federal Housing Administration (FHA), the United States Department of Agriculture (USDA) Rural Development, and the Department of Veterans Affairs (VA). These sites provide detailed guidelines, eligibility criteria, and application resources, reflecting the latest changes.
Yes, many federal programs, particularly FHA and VA, emphasize pre-purchase education and counseling. These resources are designed to equip new homebuyers with the knowledge needed to navigate the homeownership process successfully, from understanding loan terms to managing property maintenance. They are crucial for long-term homeownership success.
What this means
The New Homebuyer Benefits 2026: 3 Federal Programs Offering Significant Aid (RECENT UPDATES) signify a pivotal moment for aspiring homeowners across the United States.
These adjustments are not just bureaucratic shifts but represent a concerted effort to make homeownership more attainable and sustainable.
To explore available state-level down payment assistance and local homebuyer resources, check out California homebuyer services.
Readers should actively engage with official resources and qualified professionals to understand how these changes directly impact their personal homebuying journey.
The landscape is evolving, and staying informed is the best strategy for success in the coming years.